


September 1, 2026
Risk and Return
Do You Really Want to Be a Billionaire?

James was recently giving a seminar to young associates at a prominent venture capital firm. He talked about our ideas for sound personal financial decision making: save at least 20% of your income, pay attention to fees and taxes, watch your behavioral foibles, and keep most of your investments in index funds.
As James wrapped up, one of the associates – we’ll call him Billy – raised his hand. “But if I follow your advice,” he said, “I’ll never become a billionaire!” More than a few heads in the room nodded along.
It occurred to us that Billy might have the right answer to the wrong question. So let’s ask a better one: do you really want to maximize your probability of becoming a billionaire? And to answer this question, we need to ask, what strategy would you follow, and what distribution of wealth outcomes will you get?1
Setting Up the Problem
Let’s simplify, at the cost of some realism, to make the question easier to handle. Say Billy expects to earn about $10 million after tax over his career, and save 20% of it, or $2 million. Let’s say he has 50 years to turn that $2 million into $1 billion, a 500x increase.
Now suppose his investment opportunity set looks like this: he can flip a coin 50 times, and each flip has a 60% chance of landing on heads. On each flip, he can bet whatever fraction of his wealth he chooses. We’ll explain later why this is a reasonable, even generous, stand-in for real investment choices.
What’s the best strategy, and what probability of success does it give him? It’s a tricky problem, but it was actually solved back in 1961 in a somewhat obscure paper by UC Berkeley professor Leo Breiman.2 The answer: with the optimal strategy, Billy can achieve a 7% chance of becoming a billionaire.
The Catch
Seven percent sounds pretty good. Only about 0.001% of Americans are billionaires, and probably only around 0.05% of people who’ve managed to save $2 million ever get there.3 A 7% shot is a huge improvement.
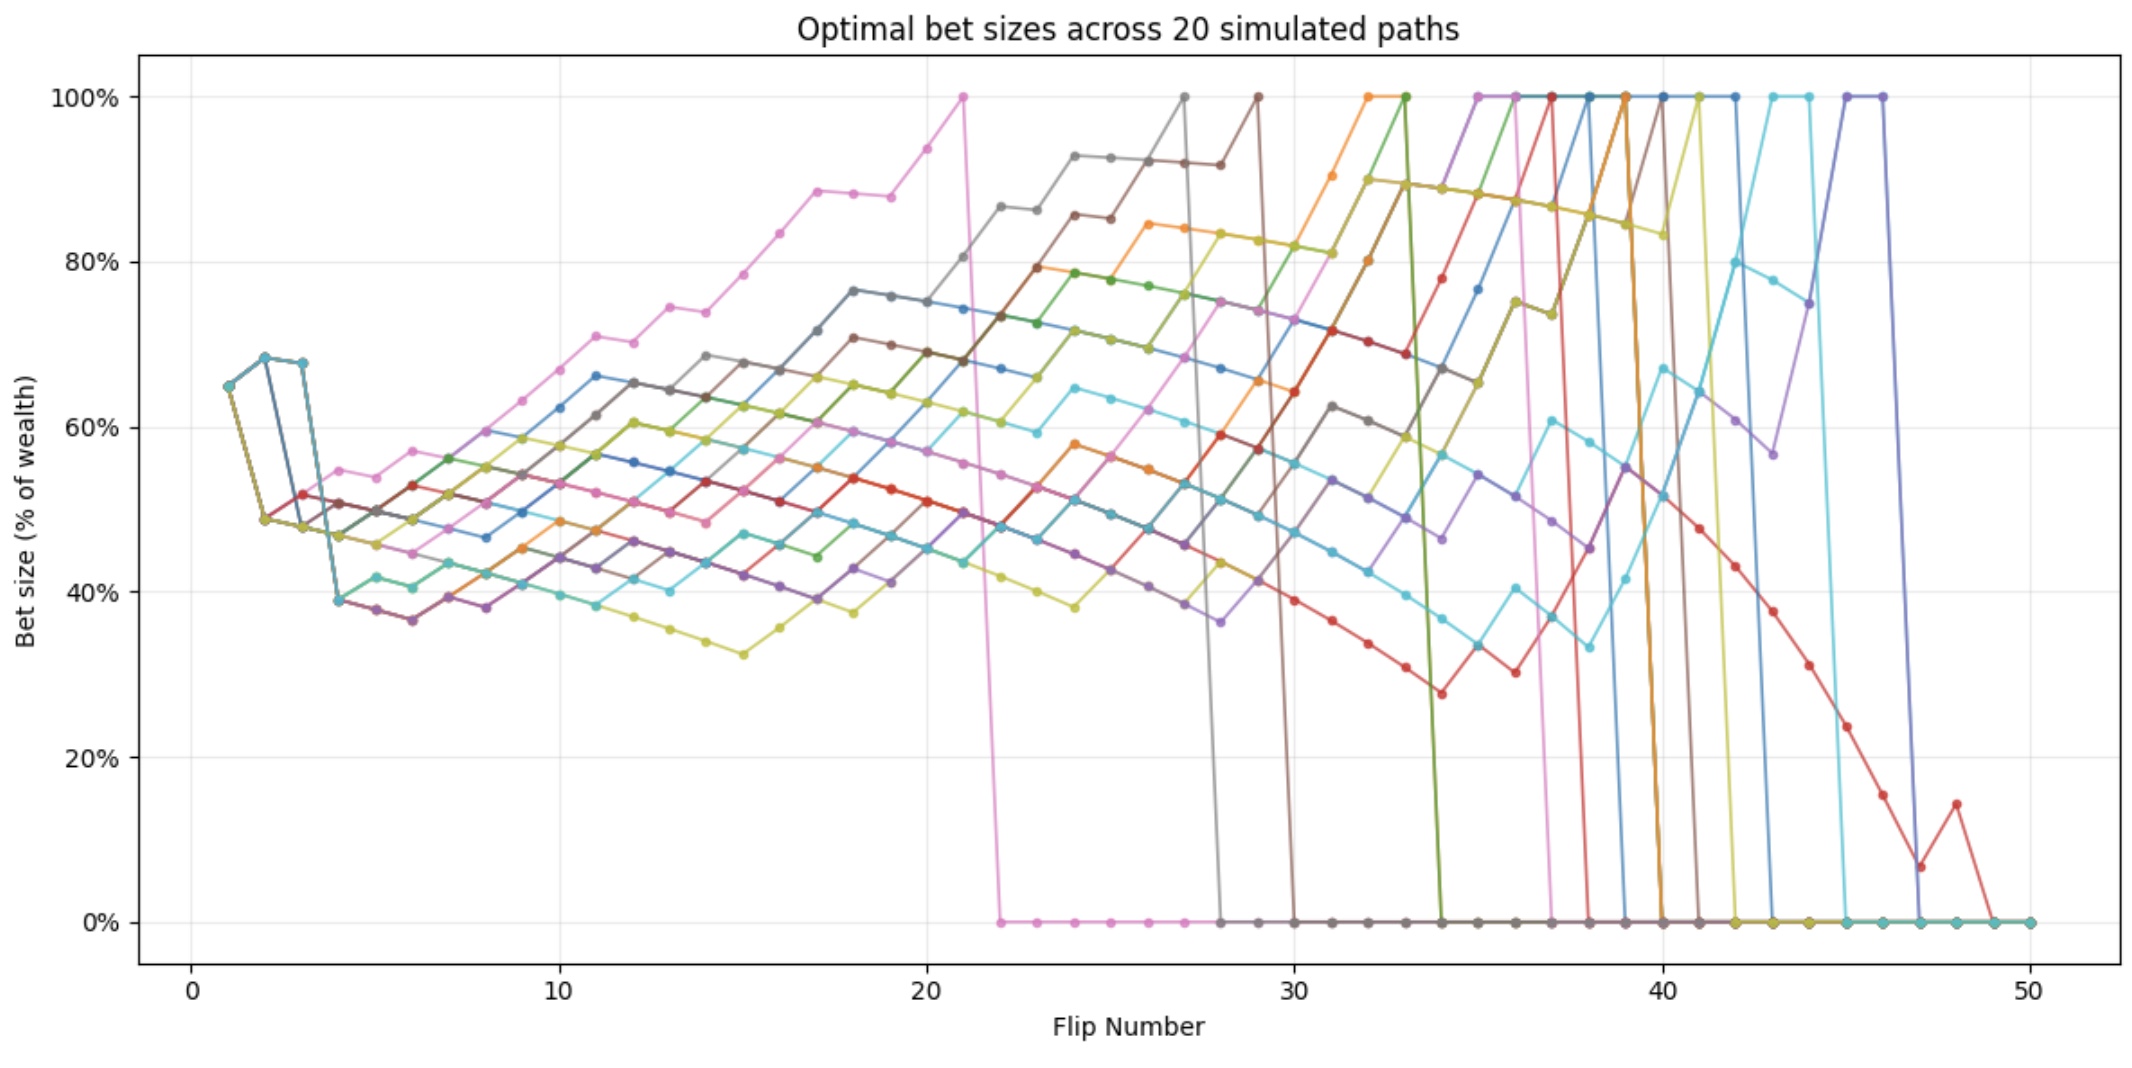
But look at the other 93% of outcomes. In those cases, Billy doesn’t just fall short of a billion – he goes broke. That’s because the strategy that maximizes his odds of hitting $1 billion requires him to routinely bet 100% of his wealth, with also means he’ll routinely go broke. Every path that doesn’t end in a billion ends instead with an all-in bet that loses. There’s no soft landing; there’s no “I’m almost a billionaire.”
What will his betting strategy actually look like? He’d start by betting about 65% of his wealth on the very first flip. That’s a lot of risk! And from there, his bet size would swing up and down depending on how he’s doing and how many flips he has left, but very often he’d end up betting 100% of his wealth on a single 60/40 coin flip. The chart below shows the optimal betting strategy across 20 simulated paths. Across all paths, his average bet size would work out to about 68% of his wealth. This isn’t an investment strategy, it’s a recipe for ruin.
Here’s another way to see how the objective of maximizing the “billionaire probability” is so strange: the strategy doesn’t change even if the odds get much worse. If Billy could only find a coin with a 51% chance of heads instead of 60%, he would follow exactly the same optimal betting pattern. The only difference is that his probability of success would drop to 0.3%, with a 99.7% chance of going bust.
Why This Fails the Sniff Test
We think a better way to make decisions under uncertainty is to maximize your expected utility. The problem with maximizing the probability of hitting an arbitrary target is that it puts all focus on that target and sacrifices everything else in service of that one goal. While Billy’s expected wealth under the probability-optimal strategy is $70 million (the 7% chance of $1 billion plus 93% of $0), his expected utility of this billionaire-or-bust strategy is effectively negative infinity. The utility of $1 billion is high, but the utility of being broke is as negative as your utility can get, and the strategy goes broke 93% of the time.
Maybe Billy tries to hedge: “I’ll set aside $1 million of my $2 million and only risk the other half, so I keep something no matter what.” That helps, a little. His odds of hitting $1 billion drop to about 4.5%, with a 95.5% chance of losing half his wealth. That still sounds pretty terrible, and his expected utility is still far worse than if he’d simply held onto his $2 million and done nothing at all.
But he can do a lot better than doing nothing at all with 50 flips of a 60/40 coin. A better option is to bet a constant and reasonable fraction of his wealth on each flip, say 10% to 20%. This is a dramatically better choice on expected-utility grounds: for a typical degree of risk aversion, such a strategy delivers a certainty-equivalent wealth roughly 1.7x what he started with.
Of course, this only works if betting a constant, modest fraction each time is compatible with his actual goals. If his goal really is “become a billionaire because life isn’t worth living if I don’t,” full stop, no reasonable strategy gets there without courting ruin.
“But What About Apple?”
Again, Billy might object: making 500 or even 1,000 times your money isn’t so far-fetched. Buy Apple, Nvidia or about 100 other amazing stocks early enough, and you’d have gotten there.
Fair enough – but first, keep in mind there have been about 30,000 companies listed in the US over the past century, so those 100 “500 baggers” are just 0.3% of the total.4 We’d say he’s better off following the optimal betting strategy on the 60/40 coin, as that gives him a 7% chance of becoming a billionaire – much better odds than picking a single stock that goes up 500-fold. Though if you’re trying to pick a 500-bagger, then most of the time when you fail you won’t be broke.
He might counter by saying, “if I use leverage of 2.5 times my savings, I just need to find a stock that goes up 200 times.” We don’t think that makes things any better, as that leverage would create a huge downward skew in the return distribution, and it generally costs a lot more than the risk-free rate to margin equities even at just 1 times your savings.
The prospective long-term Sharpe ratio of broad stock markets is in the ballpark of 0.2, just like our biased coin, and so taking 50 flips isn’t too different from having 50 years of stock-market exposure. But note that, as you take more risk beyond having 100% of your savings in equities, your return-to-risk ratio will likely go down as you’ll be getting the extra risk either through using leverage at a positive spread to the risk-free rate – or you have to take more and more idiosyncratic, non-systematic risk.
Billy is indeed correct that betting a modest 10% of your wealth on each flip gives you no chance of becoming a billionaire.5 Even the Kelly-optimal growth strategy of betting 20% gives just a 0.007% chance of getting there. If billionaire-or-bust really is the objective, sensible investing isn’t the answer. The real question is whether that should be the objective in the first place.
Connecting the Dots
We always enjoy a good coin-flipping puzzle, but the bigger point is this: the objective function you choose determines everything about the strategy that follows. As computer scientists love to say, “garbage in, garbage out.” If you choose a flawed objective, you’ll wind up with a flawed investment strategy.
Choices always require some criterion for ranking them. If you choose “maximize my probability of becoming a billionaire,” you’ll end up going broke most of the time. if you choose “maximize my expected welfare,” you’ll end up, naturally, with the highest expected welfare.
The content on this page is being provided as general market commentary and for educational purposes only. It does not constitute any form of investment advice, or recommendation to buy or sell any securities or adopt any investment strategy mentioned herein. Any investment strategies and investment results discussed herein are for illustration purposes only in the context of the commentary, and do not reflect actual or hypothetical Elm Wealth strategies or results, or an offer to provide such strategies or results.
This content is intended only to provide observations and views of the author(s) at the time of writing, both of which are subject to change at any time without prior notice. The information contained in the commentaries is derived from sources deemed by Elm Wealth to be reliable, but its accuracy and completeness cannot be guaranteed. This material does not have regard to specific investment objectives, financial situation and the particular needs of any specific reader. Any views regarding future prospects may or may not be realized. Past performance is no guarantee of future results.
- In this note, we’re not going to address whether the world already has too many billionaires – we’ll leave it to our politicians to debate that one.
- Breiman’s paper: “Optimal Gambling Systems for Favorable Games.” For readers who want a more intuitive explanation of the solution, see Jeff Rosenbluth’s article “Finite-Horizon Goal-Seeking with a Favorable Coin” on SSRN. Also, the problem was discussed in Chapter 6 of The Missing Billionaires.
- Our reasoning: 1 in 100,000 is a billionaire, and about 2,000 out of 100,000 have been able to save $2 million of their income, and 1/2,000 = 0.05%. We think this is conservative, as most billionaires get there through other pathways.
- See Bessembinder, Hendrik. (2018) “Do stocks outperform Treasury bills?” Journal of Financial Economics.
- Getting 50 heads in a row means you’ve grown your wealth by “only” 117x = 1.1050.
 Previous


